Benjamin Franklin once said that two things in life are completely unavoidable, death, and taxes. We’re not here to disagree with the founding father, but just like there are ways to preserve your health, there are ways to reduce your taxes and preserve your wealth.
Many HVAC owners focus on increasing revenue by hiring great techs and delivering exceptional service. While those priorities drive growth, there are often overlooked tax planning opportunities that could have meaningful impact on long-term wealth.
Effective tax planning isn’t about finding loopholes. It’s about proactively structuring your business and personal finances in a way that aligns with tax laws and your goals.
At JGP, we are not CPAs but proactively collaborate with them to optimize the tax strategies below.
Optimize Your Business Structure
One of the most overlooked tax decisions an HVAC business owner can make is how the business is structured.
Your entity type (Sole prop, S Corporation, LLC, etc.) directly influences how much you ultimately keep after taxes, how you pay yourself, and how effectively you can build long-term wealth inside and outside the business.
In many cases, we see owners operating under a structure that made sense when they started but may now quietly create unnecessary taxes and missed planning opportunities.
Be Intentional About How You Pay Yourself
S-Corp owners can pay themselves through salary or owner distributions. Qualifying distributions aren’t subject to employment taxes, which may reduce certain employment taxes when structured appropriately. The IRS has strict requirements that must be met before allowing owner distributions.
Finding the right balance between salary and distributions requires careful consideration of the owner’s role and macroeconomic factors in the industry. Compensation strategy is typically a large area of opportunity for HVAC owners looking for proactive tax strategies.
Take Advantage of Depreciation Opportunities
HVAC businesses regularly invest in trucks, equipment, technology, and other capital assets.
Under Internal Revenue Code (IRC) Section 168, certain qualified property may be eligible for accelerated depreciation methods, including bonus depreciation under IRC §168(k), which can allow businesses to deduct a significant portion of the cost of qualifying assets in the year they are placed in service, rather than depreciating them over several years.
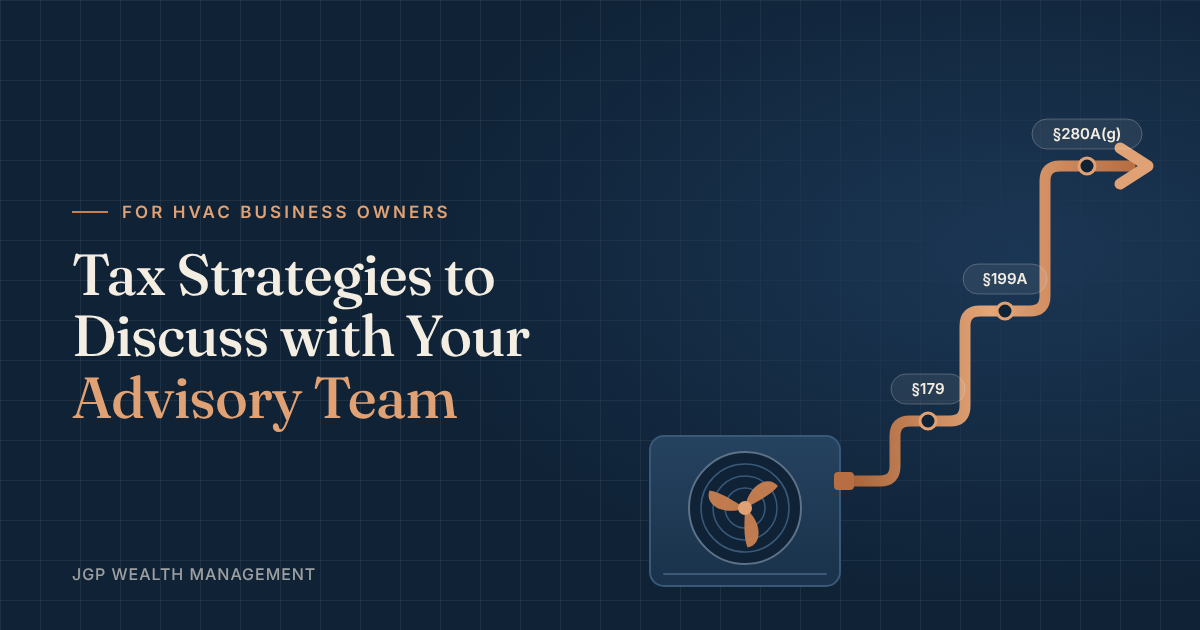
In addition, IRC Section 179 may allow businesses to elect to expense the cost of qualifying equipment in the year of purchase, subject to annual limits and taxable income thresholds.
Rather than making year-end purchases solely for a deduction, it’s often better to develop a capital investment strategy that supports both operational growth and tax efficiency.
Determine Whether You Qualify for the Qualified Business Income (QBI) Deduction
Many privately owned HVAC businesses may qualify for the Qualified Business Income (QBI) deduction under Section 199A.
For eligible businesses, this deduction can allow owners to deduct up to 20% of qualified business income, subject to various income thresholds, wage limitations, and other rules.
Because these rules can become complex as income increases, it’s important to review your eligibility annually rather than assuming you’ll automatically qualify.
Consider the Augusta Rule
The “Augusta Rule,” named after Section 280A(g) of the Internal Revenue Code, may allow business owners to rent their personal residence to their business for up to 14 days each year without recognizing the rental income on their personal tax return, provided the arrangement meets IRS requirements.
This strategy may provide a tax-efficient way to transfer funds from a business to your personal balance sheet when IRS requirements are satisfied. However, whether the business can deduct the rental expense depends on a variety of factors.
Proper documentation, reasonable rental rates, and legitimate business purposes are essential. Like many tax strategies, success depends on following the rules carefully rather than simply knowing the rule exists.
Employ Family Members Strategically
In some situations, employing family members can provide both legitimate business value and tax planning opportunities.
When appropriate, this strategy may:
- Shift income into lower tax brackets
- Teach financial responsibility
- Allow contributions to Roth IRAs or other retirement accounts if earned income requirements are met
Any compensation should reflect actual work performed and be appropriately documented. Like every strategy discussed here, proper implementation and consideration is critical.
The Bottom Line
The most successful HVAC business owners recognize that tax planning is not just about reducing this year’s tax bill. It’s about creating a long-term strategy that supports business growth, personal wealth, and future financial flexibility.
At JGP Wealth Management, we believe the best outcomes come from collaboration. Your financial advisor, CPA, and attorney each bring a unique perspective, and when those professionals work together, they can help you make informed decisions that align with your goals.
Every business owner’s situation is unique, and the strategies discussed above may or may not be appropriate depending on your circumstances. That’s why thoughtful planning—and the right advisory team—can make all the difference.
This material is provided for general educational and informational purposes only and should not be construed as individualized investment, tax, or legal advice. The strategies discussed may not be appropriate for every business owner, and their availability and effectiveness depend on individual circumstances and applicable laws. Tax laws and regulations are subject to change. JGP Wealth Management does not provide legal or tax advice. Readers should consult with their CPA, attorney, and financial advisor before implementing any strategy discussed. No particular tax outcome or financial result is guaranteed.